الصورة الرئيسية:RDNE Stock project / Pexels
احتالايات المكالمات البنكية الوهمية: اعرف حقوقك بعد الخصم المباشر
As sophisticated telephonic financial deception targets everyday consumers, understanding the mechanics behind fraudulent transactions is critical. This investigation examines how deceptive communication leads to unauthorised debits and outlines the consumer protections available under established frameworks.
The proliferation of digital banking channels has expanded economic access while simultaneously introducing complex vectors for financial fraud. Among these threats, fraudulent telephonic communications—commonly known as fake bank calls—represent a pervasive mechanism used by bad actors to extract sensitive credentials and execute unauthorised debits. Examining how these schemes operate, what recourse victims possess, and how institutional safeguards apply is essential for maintaining financial security. According to reporting by The Indian Express, understanding consumer rights following an unauthorised debit is a vital defense against digital financial deception.
Introduction to Digital Financial Deception
Digital financial deception relies on the psychological manipulation of account holders combined with technical exploitation of modern banking infrastructure. Fraudsters frequently impersonate banking institutions, regulatory bodies, or payment service providers to establish a false sense of authority and urgency. By convincing individuals that their accounts are compromised or that immediate action is required to prevent financial loss, perpetrators bypass the standard cautious behaviors that consumers typically apply to financial matters.
The consequences of falling victim to such schemes extend far beyond immediate monetary loss, eroding trust in digital payment ecosystems. When an unauthorised debit occurs, victims often face complex bureaucratic hurdles to establish liability and recover funds. Analyzing the structural nature of these scams demonstrates that they are rarely simple technical hacks; rather, they are social engineering operations that manipulate human vulnerabilities within automated banking systems.
Addressing these incidents requires a clear framework separating legitimate institutional communication from fraudulent intrusion. As investigative reporting highlights, knowing specific rights and reporting channels drastically alters a consumer’s ability to recover lost capital. This article unpacks the Anatomy of these schemes, reviews the evidentiary realities of unauthorized debits, and provides an actionable blueprint for consumer defense.
The Anatomy of the Fake Bank Call Scheme
Establishing Artificial Urgency
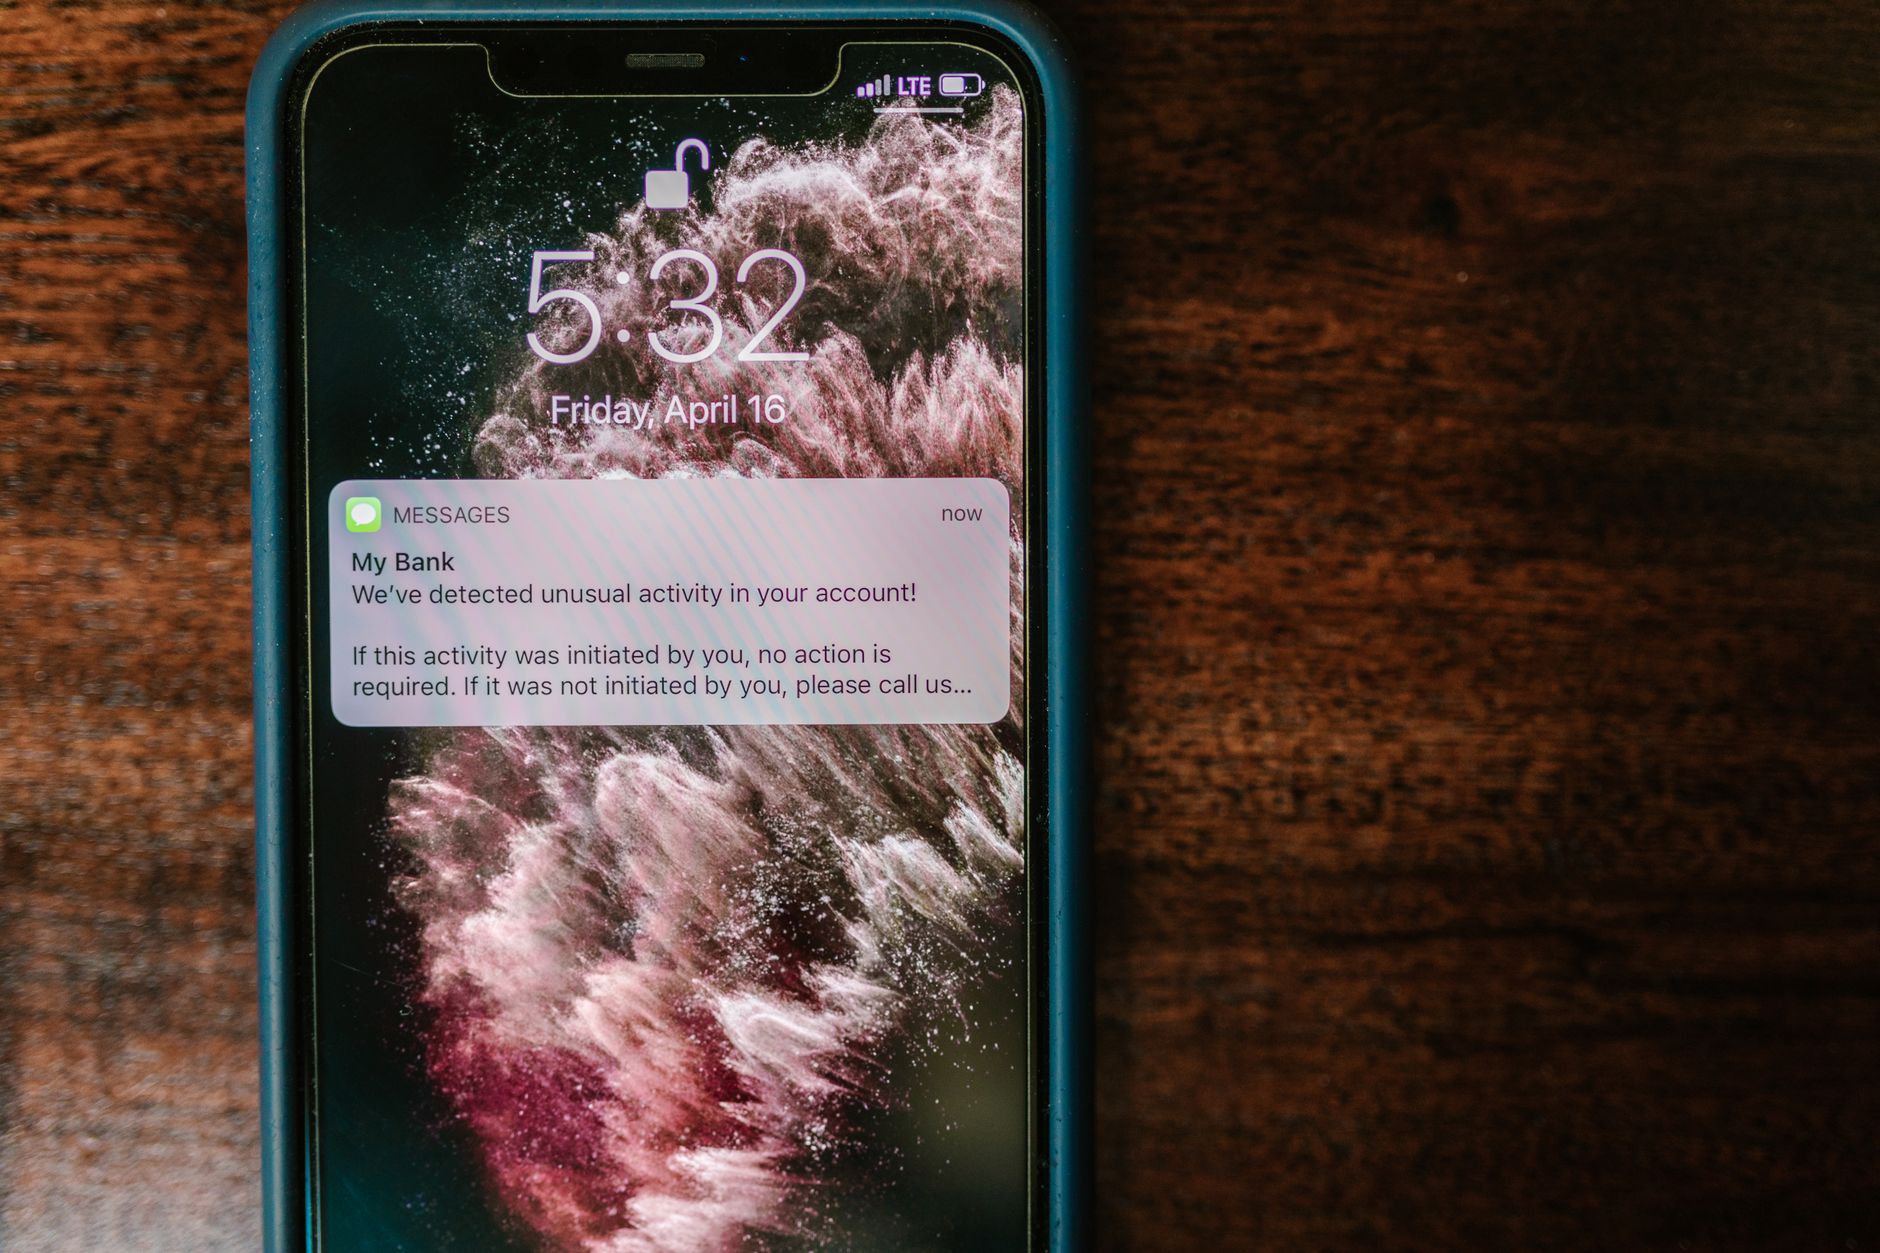
The primary vector of a fake bank call scheme is the creation of artificial urgency. Perpetrators typically contact targets via telephone, spoofing official customer service numbers to appear legitimate on caller ID displays. They often claim that an unauthorized transaction is currently attempting to clear the victim’s account, or that the account requires immediate KYC (Know Your Customer) updates to avoid suspension. This high-pressure environment is deliberately engineered to induce panic, impairing the target’s critical thinking and analytical capabilities.
Credential Harvesting and Remote Access
Once the victim is primed through fear or urgency, the fraudulent caller prompts them to divulge sensitive security information. This may include One-Time Passwords (OTPs), PINs, ATM card numbers, or login credentials for internet banking portals. In more advanced iterations, fraudsters direct victims to download third-party remote desktop applications under the guise of technical assistance. Once installed, these applications grant the perpetrator full visibility and control over the victim’s device, enabling them to bypass security protocols and execute direct fund transfers.
Transaction Routing and Layering
After acquiring unauthorized access, perpetrators act swiftly to transfer funds out of the primary account. They often utilize immediate payment services, intermediary wallets, or cryptocurrency exchanges to layer and obscure the trail of stolen money. By dispersing funds across multiple accounts in rapid succession, fraudsters complicate recovery efforts by law enforcement and bank fraud units. The speed of digital transactions works to the advantage of the criminal enterprise, making timely reporting an absolute necessity.
What the Evidence Reveals About Unauthorised Debits
Evidentiary analysis of unauthorized debit cases demonstrates that financial deception schemes exploit both human error and systematic gaps in communication verification. According to reporting by The Indian Express, victims frequently discover these breaches only after receiving transaction alert notifications or reviewing periodic account statements. Forensic examination of these incidents reveals that fraudsters rely heavily on information asymmetry, capitalizing on the fact that average consumers do not fully understand the backend mechanics of payment gateways and authorization protocols.
Data from financial fraud investigations indicate that recovery rates for unauthorized transactions are heavily dependent on the speed of notification. When a victim alerts their financial institution within a narrow timeframe—often referred to as the zero-liability or limited-liability window—the probability of freezing the funds or intercepting the transaction transfer increases significantly. Conversely, delays in reporting shift the evidentiary burden and complicate the institution’s ability to trace or recall the transferred funds.
Furthermore, evidence shows that fraudsters adapt their scripts based on prevailing economic trends and regulatory announcements. For instance, campaigns often coincide with tax seasons, holiday shopping periods, or new banking regulations, using these themes to make their pretexts appear plausible. Recognizing these patterns allows financial analysts and consumer advocates to anticipate emerging fraud vectors before they affect wider populations.
Identifying the Warning Signs of Fraudulent Calls
Distinguishing between legitimate bank communications and fraudulent attempts requires vigilance and familiarity with standard banking procedures. Financial institutions operate under strict regulatory guidelines and internal compliance protocols, which naturally limit how they handle sensitive account matters over the telephone.
| **المعالم التشغيلية** --- **الخصائص الرئيسية** {product_name} مصمم لتوفير تجربة تسوق سلسة ومتعة، مع مجموعة واسعة من الميزات التي تخدم احتياجاتك اليومية. **التسليم السريع** استمتع بتسليم سريع وموثوق، حيث نضمن وصول طلبك إلى بابك في {delivery_time} يومًا أو أقل. **الدفع الآمن** اختر من بين خيارات الدفع الآمنة مثل: - **الدفع عند الاستلام** (Cash on Delivery) - **بطاقات الائتمان/الدبيت** (Credit/Debit Cards) - **الدفع عبر PayPal** (PayPal) - **الدفع عبر مودل** (Mada) **الخدمة العملاقة** نحن هنا لدعمك في كل خطوة، من اختيار المنتج حتى تسليمه. إذا كان لديك أي أسئلة، اتصل بنا عبر: 📞 **الهاتف**: {phone_number} ✉️ **البريد الإلكتروني**: {support_email} **الضمان والرجوع** نحن نقدم ضمانًا على جميع المنتجات لمدة {warranty_period} شهرًا. إذا لم تكن راضيًا عن منتجك، يمكنك إرجاعه خلال {return_period} أيام دون أي أسئلة. **التسوق الآمن** - **تشفير البيانات**: جميع بياناتك آمنة معنا، حيث نستخدم تقنية التشفير المتقدمة. - **الخصوصية**: نحرص على حماية بياناتك الشخصية وفقًا لأعلى معايير الأمان. **الخصومات والهدايا** استفد من عروضنا اليومية والحصرية: - **خصم {discount_percentage}%** على أول طلب. - **هدايا مجانية** مع كل طلب بقيمة {minimum_order_value} ريال أو أكثر. **الاستفسارات الشائعة** - **هل يمكنني تغيير طلبي بعد الدفع؟** نعم، يمكنك تغيير طلبك خلال {order_change_period} ساعة من الدفع. - **ما هي سياسة الإرجاع؟** يمكنك إرجاع المنتجات غير المفتوحة خلال {return_period} أيام، مع استرداد كامل للرسوم. - **كيف يمكنني تتبع طلبي؟** استخدم الرابط التالي لتتبع طلبك: {tracking_link} **التسوق الآن** {cta_button_text} **المنتجات المميزة** {featured_products_shortcode} **المنتجات الأكثر مبيعًا** {best_sellers_shortcode} **العلامات التجارية المفضلة** {brand_shortcode} **الاشتراك في النشرة الإخبارية** {newsletter_signup_shortcode} **الاشتراك في برنامج الولاء** {loyalty_program_shortcode} **الاستعراضات** {reviews_shortcode} **الاستفسارات** {contact_form_shortcode} **السياسات** - [سياسة الخصوصية]({privacy_policy_link}) - [شروط الاستخدام]({terms_link}) - [سياسة الإرجاع]({return_policy_link}) **الشبكات الاجتماعية** {social_media_shortcode} | Legitimate Bank Communication | Fraudulent Fake Bank Call |
|---|---|---|
| Request for Credentials | Never asks for OTPs, PINs, or full passwords over the phone. | Demands immediate disclosure of OTPs, PINs, or passwords. |
| Tone and Pressure | Professional, calm, and guides customer through formal channels. | Aggressive, urgent, and threatens immediate account blocking or legal action. |
| Call Initiation | Usually inbound from customer, or outbound via verified automated systems. | Unsolicited cold call, often utilizing spoofed or masked numbers. |
| Software Downloads | Never instructs users to install third-party remote access software. | Insists on downloading screen-sharing or remote desktop applications. |
Consumer Rights Following an Unauthorised Debit
The Principle of Limited Liability
Consumers who fall victim to unauthorized electronic banking transactions are protected by regulatory frameworks that limit their financial liability, provided they report the incident promptly. Under established banking Ombudsman and regulatory guidelines, liability is determined based on who is at fault for the security lapse. If the unauthorized transaction occurs due to a systemic flaw, breach, or negligence on the part of the bank, the customer bears zero liability.
Reporting Timeframes and Liability Tiers
Where the unauthorized debit occurs due to third-party fraud—such as a fake bank call where the customer inadvertently shares credentials—liability depends heavily on how quickly the incident is reported. Reporting the unauthorized transaction within a very short window (typically zero to three days) often shields the consumer from financial loss under zero-liability provisions. If reported between four and seven days, the consumer’s liability is generally capped at a lower, specified amount. Delays exceeding seven days typically result in the customer bearing the full loss, governed by the bank’s board-approved policies.
Burden of Proof
In cases of disputed transactions resulting from digital deception, the burden of proof rests largely on the financial institution to establish customer negligence. The bank must demonstrate that the customer authorized the transaction through multi-factor authentication or grossly negligent behavior, such as explicitly sharing their PIN or OTP despite clear institutional warnings. Consumers retain the right to dispute findings and escalate unresolved grievances to banking ombudsmen or consumer protection forums.
Institutional and Regulatory Responses to Bank Scams
Financial institutions, regulatory bodies, and telecommunications companies are increasingly implementing technological countermeasures to combat the rise of fake bank calls. Banks have deployed advanced transaction monitoring systems that analyze spending patterns in real-time, automatically flagging and temporarily freezing transactions that deviate significantly from a customer’s normal behavior.
On the regulatory front, central banks and consumer protection agencies have mandated stricter authentication protocols, such as two-factor authentication (2FA) for all digital transactions and tighter controls over the issuance of remote access permissions. Furthermore, telecommunications regulators are working in coordination with law enforcement to filter out spoofed international numbers and block fraudulent calling lines used by cyber syndicates.
Despite these institutional efforts, fraudsters continuously evolve their tactics to exploit gaps between regulatory updates and technical enforcement. Consequently, institutional responses must be complemented by continuous public awareness campaigns that educate consumers on emerging fraud methodologies and emphasize the importance of immediate incident reporting.
Actionable Steps to Take After Falling Victim
If you or someone you know has been targeted by a fake bank call and experienced an unauthorised debit, immediate action is critical to mitigate further loss and preserve recovery options. Follow this structured protocol:
- Contact your bank’s fraud helpline immediately to report the unauthorized transaction and request the immediate freezing or blocking of all associated debit cards, credit cards, and net banking access.
- Note down the transaction reference numbers, date, time, and the exact details of the communication received, including any phone numbers displayed on your caller ID.
- File a formal complaint with the local cybercrime cell or law enforcement agency, ensuring you obtain a copy of the official complaint or First Information Report (FIR) for your records.
- Lodge a formal dispute ticket with your bank in writing, explicitly referencing the timeline of reporting to claim protection under limited liability regulations.
- Change all your digital banking passwords, secure your email accounts, and uninstall any unfamiliar remote access applications that may have been installed during the fraudulent call.
قائمة العلامات الحمراء
- Unsolicited calls claiming urgent account suspension or KYC expiry.
- Callers requesting One-Time Passwords (OTPs), ATM PINs, or UPI handles.
- Instructions to download unfamiliar remote desktop or screen-sharing software.
- Callers exhibiting aggressive, threatening, or high-pressure communication styles.
- Discrepancies between official bank helpline numbers and the incoming caller ID.
الأسئلة الشائعة
What is a fake bank call scam?
A fake bank call scam is a form of digital financial deception where fraudsters impersonate bank representatives over the phone to trick victims into revealing sensitive credentials or authorizing fraudulent money transfers.
Am I liable for money lost through an unauthorised debit?
Your liability depends on when you report the incident. If reported immediately within the mandated regulatory window, you may be eligible for zero liability, whereas delayed reporting can result in financial loss.
Can a bank reverse an unauthorized transaction after it has cleared?
While recovery is challenging once funds are transferred, banks and law enforcement can sometimes freeze or recall funds if the unauthorized transaction is reported instantly and traced through intermediary payment channels.
What should I do immediately if I share my OTP during a scam call?
You must contact your bank immediately to block your accounts and cards, change your secure credentials, and file a formal fraud complaint with the cybercrime authorities.
Do banks ever ask for OTPs or PINs over the phone?
No. Legitimate banking institutions and customer service representatives will never ask for your OTP, ATM PIN, or full internet banking password under any circumstances.