Imagem principal:Elise / Pexels
Leis sobre ATM de Criptomoeda no Wisconsin: Avaliando Seu Impacto em Golpes
Uma análise embasada em evidências sobre como novos quadros regulatórios abordam fraudes em ativos digitais. Esta investigação analisa a eficácia da legislação sobre caixas eletrônicos de criptomoedas do Wisconsin no combate a esquemas financeiros enganosos, baseando-se exclusivamente em relatórios documentados.
Cryptocurrency automated teller machines have become a prominent vector for financial fraud, prompting state legislatures to enact targeted regulatory measures to protect consumers. In Wisconsin, policymakers introduced and passed specific legislative frameworks designed to curb the exploitation of these physical terminals by bad actors. However, assessing the practical effectiveness of these statutes requires a rigorous examination of enforcement data, victim demographics, and the structural mechanics of how these scams operate. As regulatory bodies attempt to outpace evolving deception techniques, understanding what evidence actually shows about these laws is critical for consumers, regulators, and financial investigators alike.
Contexto e Fundamentos da Legislação
The proliferation of cryptocurrency kiosks in convenience stores, gas stations, and shopping centers created an unregulated or loosely regulated highway for cash-to-crypto conversions. These physical terminals allow individuals to deposit fiat currency in exchange for digital assets, which are then immediately transferred to external wallet addresses. Because cash transactions are largely irreversible and digital asset transfers lack the chargeback protections inherent in traditional banking, fraudsters quickly identified these machines as ideal channels for laundering money and extracting funds from victims.
To combat this rising tide of financial deception, state lawmakers pursued legislative interventions aimed at increasing transparency and accountability around physical crypto kiosks. According to reporting by PBS Wisconsin, the legislative process involved establishing clearer operational guardrails for kiosk operators and implementing consumer protection mechanisms designed to interrupt fraudulent transactions before funds leave the victim’s possession. These rules seek to bridge the gap between traditional money transmitter regulations and the decentralized, rapid-fire nature of blockchain transactions.
The primary intent behind the Wisconsin framework was to introduce friction into the scam process. By imposing disclosure requirements, transaction limits, or mandatory warning notices directly on the kiosk interfaces, lawmakers hoped to give unsuspecting victims a critical moment of pause. According to PBS Wisconsin, these policy efforts reflect a broader nationwide recognition that municipal and federal consumer protection agencies alone cannot manage the localized deployment of thousands of cash-to-crypto terminals without state-level enforcement capabilities.
The Mechanics of Crypto ATM Scams
Impersonation and Urgency Tactics
Fraudsters utilizing crypto ATMs rarely approach victims with an overt request to purchase digital currency for investment. Instead, they rely on elaborate impersonation schemes where the victim believes they are interacting with a legitimate authority figure, such as a law enforcement officer, a bank fraud investigator, or a representative from a utility company or government agency. PBS Wisconsin highlighted that these scammers manufacture a false sense of immediate crisis—claiming, for instance, that the victim’s bank accounts have been compromised, that a warrant is out for their arrest, or that their assets must be converted to cryptocurrency to be secured by a government entity.
The Cash-to-Crypto Conversion Loop
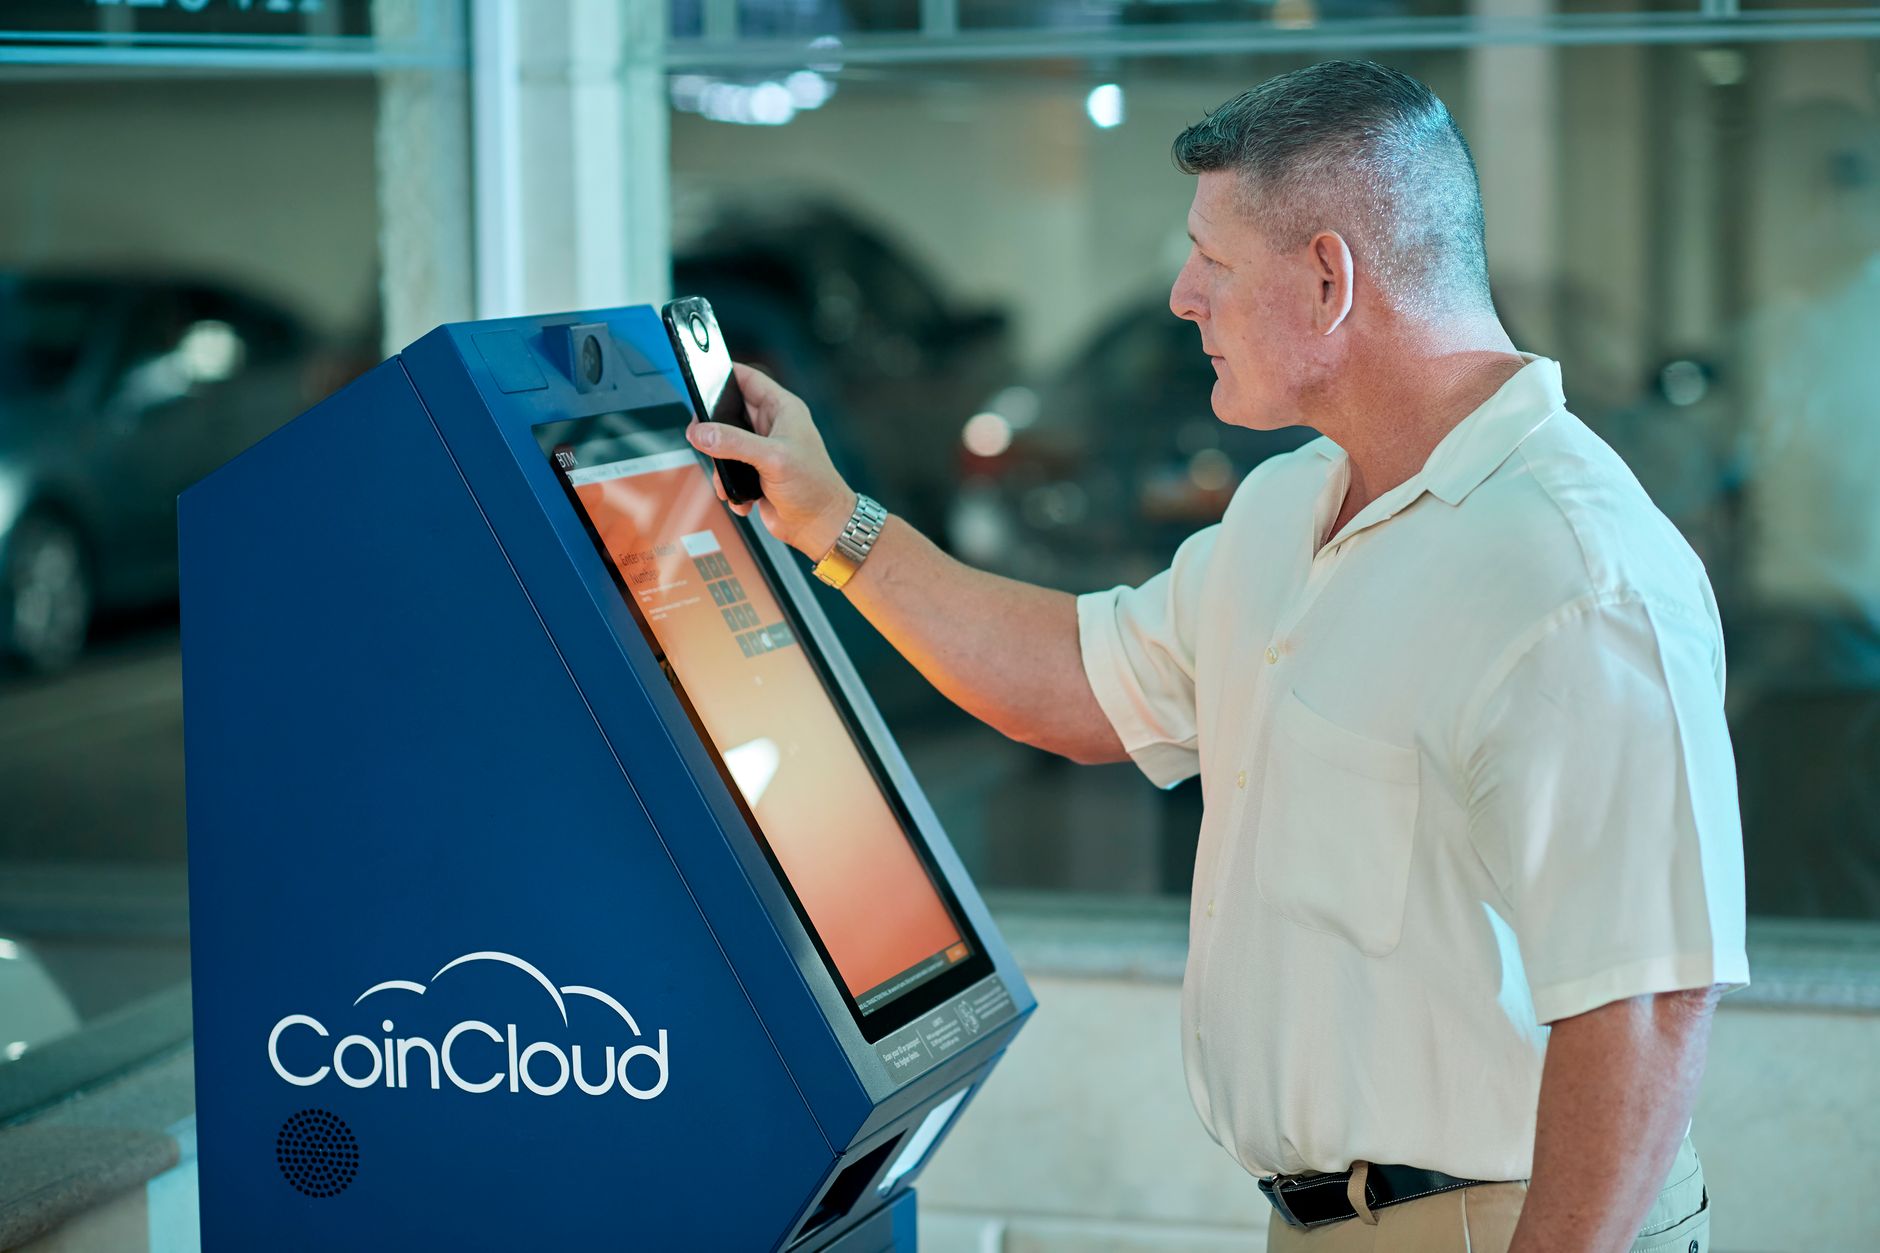
Once the victim is psychologically primed and operating under acute stress, the perpetrator directs them to the nearest physical cryptocurrency kiosk. The mechanics of this phase are specifically engineered to bypass traditional institutional oversight. Unlike a bank teller who might question a large, unusual cash withdrawal, a crypto ATM operates autonomously. The victim withdraws physical cash from their bank, drives to the designated terminal, feeds the cash bills into the machine, and scans a QR code provided by the scammer. PBS Wisconsin noted that this QR code encodes the destination wallet address controlled entirely by the criminal enterprise, ensuring that the transferred funds vanish instantly beyond the reach of standard recovery mechanisms.
Exploiting Technological Unfamiliarity
A core driver of crypto ATM vulnerability is the profound technological barrier separating the average consumer from the mechanics of blockchain transactions. Many victims who use these kiosks have never previously owned or purchased digital assets. Fraudsters exploit this knowledge gap by walking victims through every step of the kiosk interface via phone calls or messaging apps, effectively acting as remote handlers. By maintaining continuous verbal contact, the perpetrator ensures the victim does not notice warning labels on the machine or question the bizarre nature of depositing cash into a kiosk to resolve a municipal or banking issue.
What Evidence Shows Regarding the New Law
Evaluating Real-World Efficacy
When measuring the success of financial regulations, empirical data remains the ultimate arbiter. However, evaluating the precise impact of Wisconsin’s crypto ATM law presents distinct analytical challenges. According to reporting by PBS Wisconsin, determining the exact volume of scams prevented by the legislation is difficult because prevented crimes often go unreported, and fraudulent enterprises continually adapt their operational methods to circumvent newly established legal bottlenecks.
Operator Compliance and Enforcement Challenges
The enforcement of kiosk-specific regulations relies heavily on the cooperation of ATM operators and the investigative capacity of local and state regulatory agencies. PBS Wisconsin pointed out that while statutory frameworks set clear rules regarding disclosures and transaction thresholds, rogue operators or out-of-state entities sometimes attempt to bypass compliance obligations. Regulatory bodies face ongoing hurdles in monitoring thousands of decentralized terminals distributed across geographically diverse retail locations, making proactive compliance verification a resource-intensive endeavor.
The Discrepancy Between Statute and Execution
Legal mandates written on paper do not automatically translate into behavioral shifts on the ground. While the law mandates specific consumer warnings and operational transparency, skeptical oversight suggests that determined scammers simply pivot to alternative psychological manipulation scripts that neutralize these warnings. According to PBS Wisconsin, victims under severe emotional coercion often ignore on-screen prompts or are instructed by scammers to lie to kiosk staff or bystanders about the purpose of their transactions, highlighting the limits of purely interface-based legislative remedies.
Demographics and Impact on Victims
Disproportionate Targeting of Older Adults
Data consistently demonstrates that financial scams involving physical crypto kiosks disproportionately impact specific segments of the population, most notably older adults. According to reporting by PBS Wisconsin, seniors are frequently targeted by fraudsters who exploit generational trust in institutional authority, such as courts, federal agencies, and traditional banking institutions. The unfamiliarity of older demographics with digital asset architecture makes them uniquely susceptible to complex impersonation narratives that require converting physical savings into cryptocurrency.
Psychological and Financial Devastation
The financial losses incurred through crypto ATM fraud are rarely negligible; they frequently represent the entirety of a victim’s retirement savings or liquid emergency funds. PBS Wisconsin emphasized that unlike credit card fraud, where consumers enjoy robust federal liability protections and chargeback rights, cash deposited into a crypto ATM and converted on a public blockchain is virtually impossible to recover. This creates profound secondary impacts, including severe psychological distress, loss of housing stability, and long-term dependency on family members or social support systems.
Isolation as a Vulnerability Factor
A recurring pattern identified in investigative reporting is the role of social isolation in exacerbating victim vulnerability. Fraudsters routinely instruct victims to maintain absolute secrecy, telling them not to discuss the “investigation” or “security transfer” with family members, friends, or bank personnel. PBS Wisconsin noted that this enforced isolation cuts off the victim from external reality checks that might otherwise disrupt the scam before cash is converted at a kiosk terminal.
Red Flags in Cryptocurrency ATM Fraud
- Being instructed by a government, utility, or law enforcement official to withdraw cash and deposit it into a cryptocurrency ATM.
- Claims that your bank accounts are unsafe and that funds must be converted to digital assets to protect them from seizure or hacking.
- Receiving a QR code from an unknown third party via text, email, or phone to scan at a physical kiosk terminal.
- Requests for absolute secrecy or instructions not to talk to bank tellers, family members, or store employees about the transaction.
- Promises of guaranteed, risk-free financial returns or demands to pay upfront fees in cryptocurrency to claim a lottery win or grant.
- Urgency tactics insisting that financial transactions must be completed within minutes or hours to avoid arrest or legal penalties.
Respostas Institucionais e Regulatórias
Beyond state-level statutes, combatting crypto ATM fraud requires a coordinated multi-institutional response involving law enforcement, financial intelligence units, and retail partners. According to PBS Wisconsin, consumer protection agencies and state regulators are increasingly collaborating to audit kiosk operators, penalize non-compliant networks, and raise public awareness through targeted educational campaigns. These institutional efforts aim to hold operators accountable for failing to implement basic anti-fraud protocols on their machines.
Retail establishments that host cryptocurrency ATMs are also facing mounting scrutiny regarding their role in hosting these terminals. While store owners often receive rental income or transaction commissions for housing the kiosks, public interest groups and investigative reports indicate a growing moral and operational responsibility to monitor suspicious activity near the machines. PBS Wisconsin highlighted that empowering retail staff to recognize victims in distress—such as an elderly customer purchasing thousands of dollars in crypto while visibly agitated on a cell phone—serves as a vital human firewall against financial deception.
Furthermore, federal oversight bodies, including the Federal Trade Commission and the Consumer Financial Protection Bureau, track the macro trends of digital asset exploitation. Their data informs state legislators like those in Wisconsin, helping shape subsequent legislative amendments that close loopholes exploited by criminal syndicates. This feedback loop between federal macro-data and state micro-enforcement is essential for adapting regulatory frameworks to an ever-evolving criminal landscape.
Recommended Actions for Consumers
Protecting oneself and vulnerable family members from crypto ATM fraud requires adopting strict verification habits and maintaining a healthy skepticism toward unsolicited financial instructions. Consumers should keep the following actionable guidance in mind:
- Never convert physical cash into cryptocurrency at the behest of someone you have only met online or over the telephone.
- Verify the identity of anyone claiming to be a law enforcement officer, government official, or bank investigator by independently calling official, published phone numbers rather than numbers provided by the caller.
- Recognize that government agencies, courts, and utility companies never accept cryptocurrency payments or demand cash transfers via public ATM kiosks.
- Establish open lines of communication regarding financial decisions with trusted family members or financial advisors, especially if sudden or unusual asset movements are contemplated.
- Report suspected fraud immediately to local law enforcement, the state consumer protection agency, and federal reporting portals such as the Federal Trade Commission or the FBI Internet Crime Complaint Center.
Perguntas Frequentes
What is a cryptocurrency ATM?
A cryptocurrency ATM is a physical kiosk that allows users to purchase digital assets like Bitcoin using physical cash or debit cards, or occasionally to sell digital currency for cash. Unlike traditional bank ATMs, these machines interface directly with blockchain networks and decentralized wallet addresses.
Why do scammers prefer crypto ATMs over traditional bank transfers?
Scammers favor crypto ATMs because cash transactions and blockchain transfers are instantaneous and irreversible. Unlike wire transfers or credit card payments, there are no intermediary financial institutions capable of freezing the transaction or issuing chargebacks once the funds are sent.
How does Wisconsin’s crypto ATM law attempt to stop fraud?
According to PBS Wisconsin, the law introduces regulatory oversight, operational compliance standards, and mandatory warning notices or transaction controls on kiosks to alert consumers and limit the unauthorized movement of funds by bad actors.
Can money lost through a crypto ATM scam be recovered?
Recovery of funds lost through crypto ATM scams is exceedingly rare. Once cash is deposited into a machine and converted into cryptocurrency sent to an external wallet, the transaction is anonymous, decentralized, and final.
What should I do if I suspect someone is falling victim to a crypto ATM scam?
If you observe someone—particularly an older adult—acting distressed while attempting to deposit large amounts of cash into a crypto ATM under instructions from a phone call, interrupt them gently, advise them to halt the transaction, and contact local law enforcement immediately.